The Dominican Republic’s proposed 55% ad-valorem selective tax on electronic cigarettes and vaping devices, introduced under Article 43 of the “Ley 30-26 de Medidas Pro-Crecimiento Económico, Simplificación Fiscal y Mitigación de la Crisis Internacional,” has reignited a fierce debate among economists and public health advocates. By attempting to align the fiscal burden of vapes with that of conventional cigarettes, policymakers risk undermining public health goals and driving a massive surge in the illicit market, repeating costly historical mistakes.
While no advocate claims that vaping products are entirely harmless, extensive scientific literature establishes them as a significantly less harmful substitute for combustible tobacco. However, some local analysts, such as Edgar Morales, argue that because e-cigarettes and traditional cigarettes satisfy the same underlying consumer need, they should face equivalent tax burdens. This simplified logic overemphasizes short-term revenue collection at the absolute expense of public health and economic reality.
The Misapplication of Pigouvian Taxation
To understand why this tax is fundamentally flawed, one must look to the economic theories of Arthur Cecil Pigou. In his seminal work, The Economics of Welfare, Pigou introduced “sin taxes” designed to correct negative externalities – the societal costs of private consumption. In a modern regulatory framework, Pigouvian taxes must be risk-proportionate. They should incentivize consumers to migrate from high-risk products to lower-risk alternatives.
Equating vapes with combustible cigarettes ignores the critical scientific differentiator: combustion. It is not nicotine alone that drives the severe negative externalities of smoking, but the combustion process of traditional cigarettes, which releases thousands of toxic chemicals and carcinogens. Because vaping does not involve combustion, its negative health externalities are demonstrably lower. Therefore, applying identical tax rates to both categories violates basic economic and public health principles.
International Benchmarks and IMF Guidelines
Contrary to local arguments, taxing vapes at the same rate as combustible cigarettes is an international exception, not the standard. Academic research, including a prominent study by Arozamena et al., demonstrates that optimal taxation for “sin products” should be risk-adjusted and rely on specific taxes (based on volume or nicotine content) rather than volatile ad-valorem taxes.
Furthermore, the International Monetary Fund (IMF), in its publication “Taxing Sin” (Gravar los malos hábitos), outlines three core principles for optimizing excise taxes on tobacco and nicotine products:
- Broad Coverage: All nicotine consumption options must be taxed to prevent tax evasion and unregulated market gaps.
- International Cooperation: Enforcement must be strengthened globally to combat illicit trade and cross-border smuggling.
- Risk-Aligned Rates: Tax rates must directly correspond to the relative negative externality of each product. The IMF explicitly states that because reduced-risk products limit exposure to toxins, they should be taxed at lower rates than combustible tobacco.

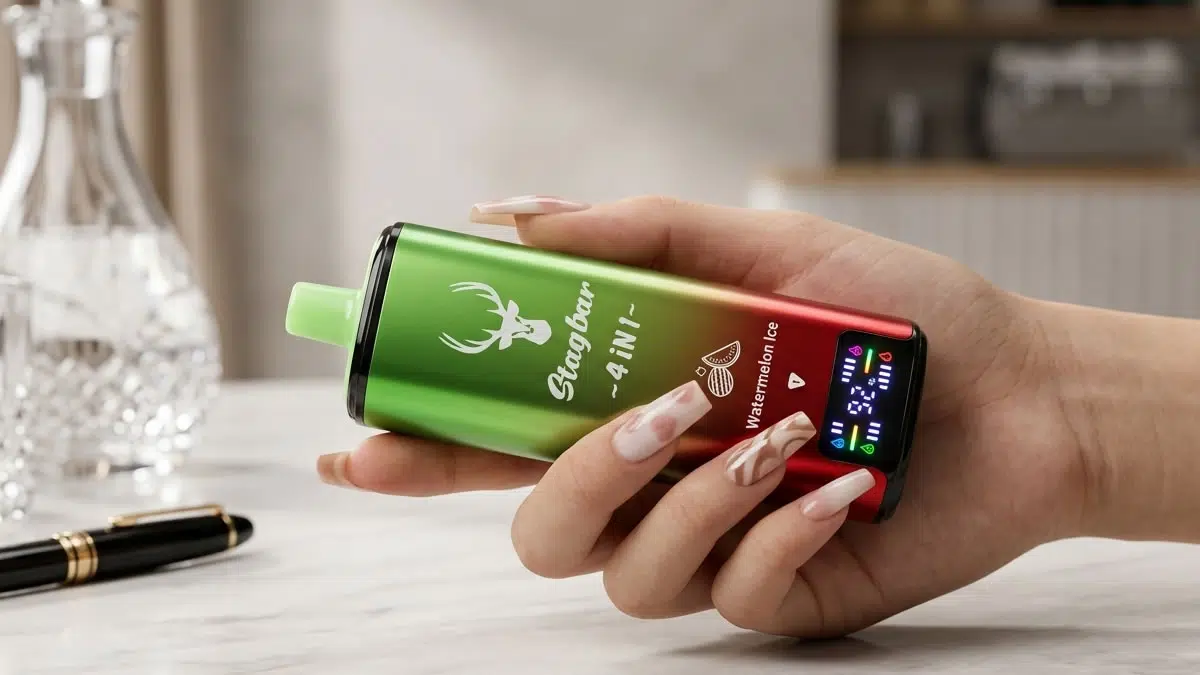
StagBar Vape 6in1 180K Puffs Disposable
The Stagbar 6-in-1 featuring a unique 6-flavor system and six independent mesh coils, this device allows users to switch between six distinct tastes in one sleek unit, delivering an unprecedented 180,000 puffs.
The Economic Reality: Price Shocks and Low-Income Impact
If the 55% ad-valorem tax is implemented, the economic consequences for Dominican consumers will be immediate and severe. Industry projections indicate that the average retail price of a vaping device will skyrocket by approximately 90%, jumping from RD$450.00 to RD$854.00. This increase would give the Dominican Republic some of the most expensive vaping products globally.
Crucially, demographic data reveals that nearly 70% of vape users in the Dominican Republic reside in low-income households. A price shock of this magnitude will not force these users to quit nicotine. Instead, it will drive them toward two dangerous alternatives: cheap, unregulated black-market vapes, or highly toxic, low-cost combustible cigarettes.
| Market Metric | Current State | Projected State (Under Ley 30-26) | Percentage Change |
|---|---|---|---|
| Average Vape Price | RD$ 450.00 | RD$ 854.00 | +90% |
| Legal Market Volume | 100% (Baseline) | 25% | -75% |
| Low-Income Consumer Share | ~70% of total users | Displaced to illicit/combustible market | Significant risk shift |
Learning from the 2012 Fiscal Failure
The Dominican Republic has already experienced the damaging effects of excessive selective taxation. During the 2012 fiscal reform, the government implemented aggressive tax hikes on alcohol and tobacco products. Rather than increasing revenues, the high tax rates caused legal consumption to collapse as consumers turned to illicit contraband.
The resulting drop in tax collection forced the state to pass Law No. 175-07 (“Reducción de Tasas para el Sector de Bebidas Alcohólicas y el Tabaco”) to lower tax rates, curb smuggling, and stabilize government revenues. History shows that when tax rates exceed the market’s economic tolerance, the state loses both regulatory control and tax revenue.
Conclusion: A Public Health and Fiscal Lose-Lose
Fiscal differentiation between vapes and combustible cigarettes is not a corporate privilege; it is an essential public health tool. By maintaining a clear price gap, the government can financially incentivize smokers to transition away from combustible tobacco, which carries the highest health risks.
By ignoring scientific evidence and international best practices, the 55% ad-valorem tax under Ley 30-26 is poised to fail on two fronts. It will jeopardize public health by driving users back to smoking or unregulated black-market products, and it will fail to meet revenue expectations due to a projected 75% collapse in the legal market. To avoid this lose-lose outcome, Dominican policymakers must integrate public health data with fiscal strategy, opting for a moderate, specific tax rather than an excessive ad-valorem levy.







